On this page
India’s grocery market spans family-run kirana stores, regional supermarkets, national value chains, premium specialists, online marketplaces and rapid-delivery apps. A single “top supermarkets” ranking hides those differences and quickly becomes obsolete. This guide compares active grocery groups and formats using current company disclosures. Store counts are shown only when a company or recent annual report states them.
How India’s grocery formats fit together
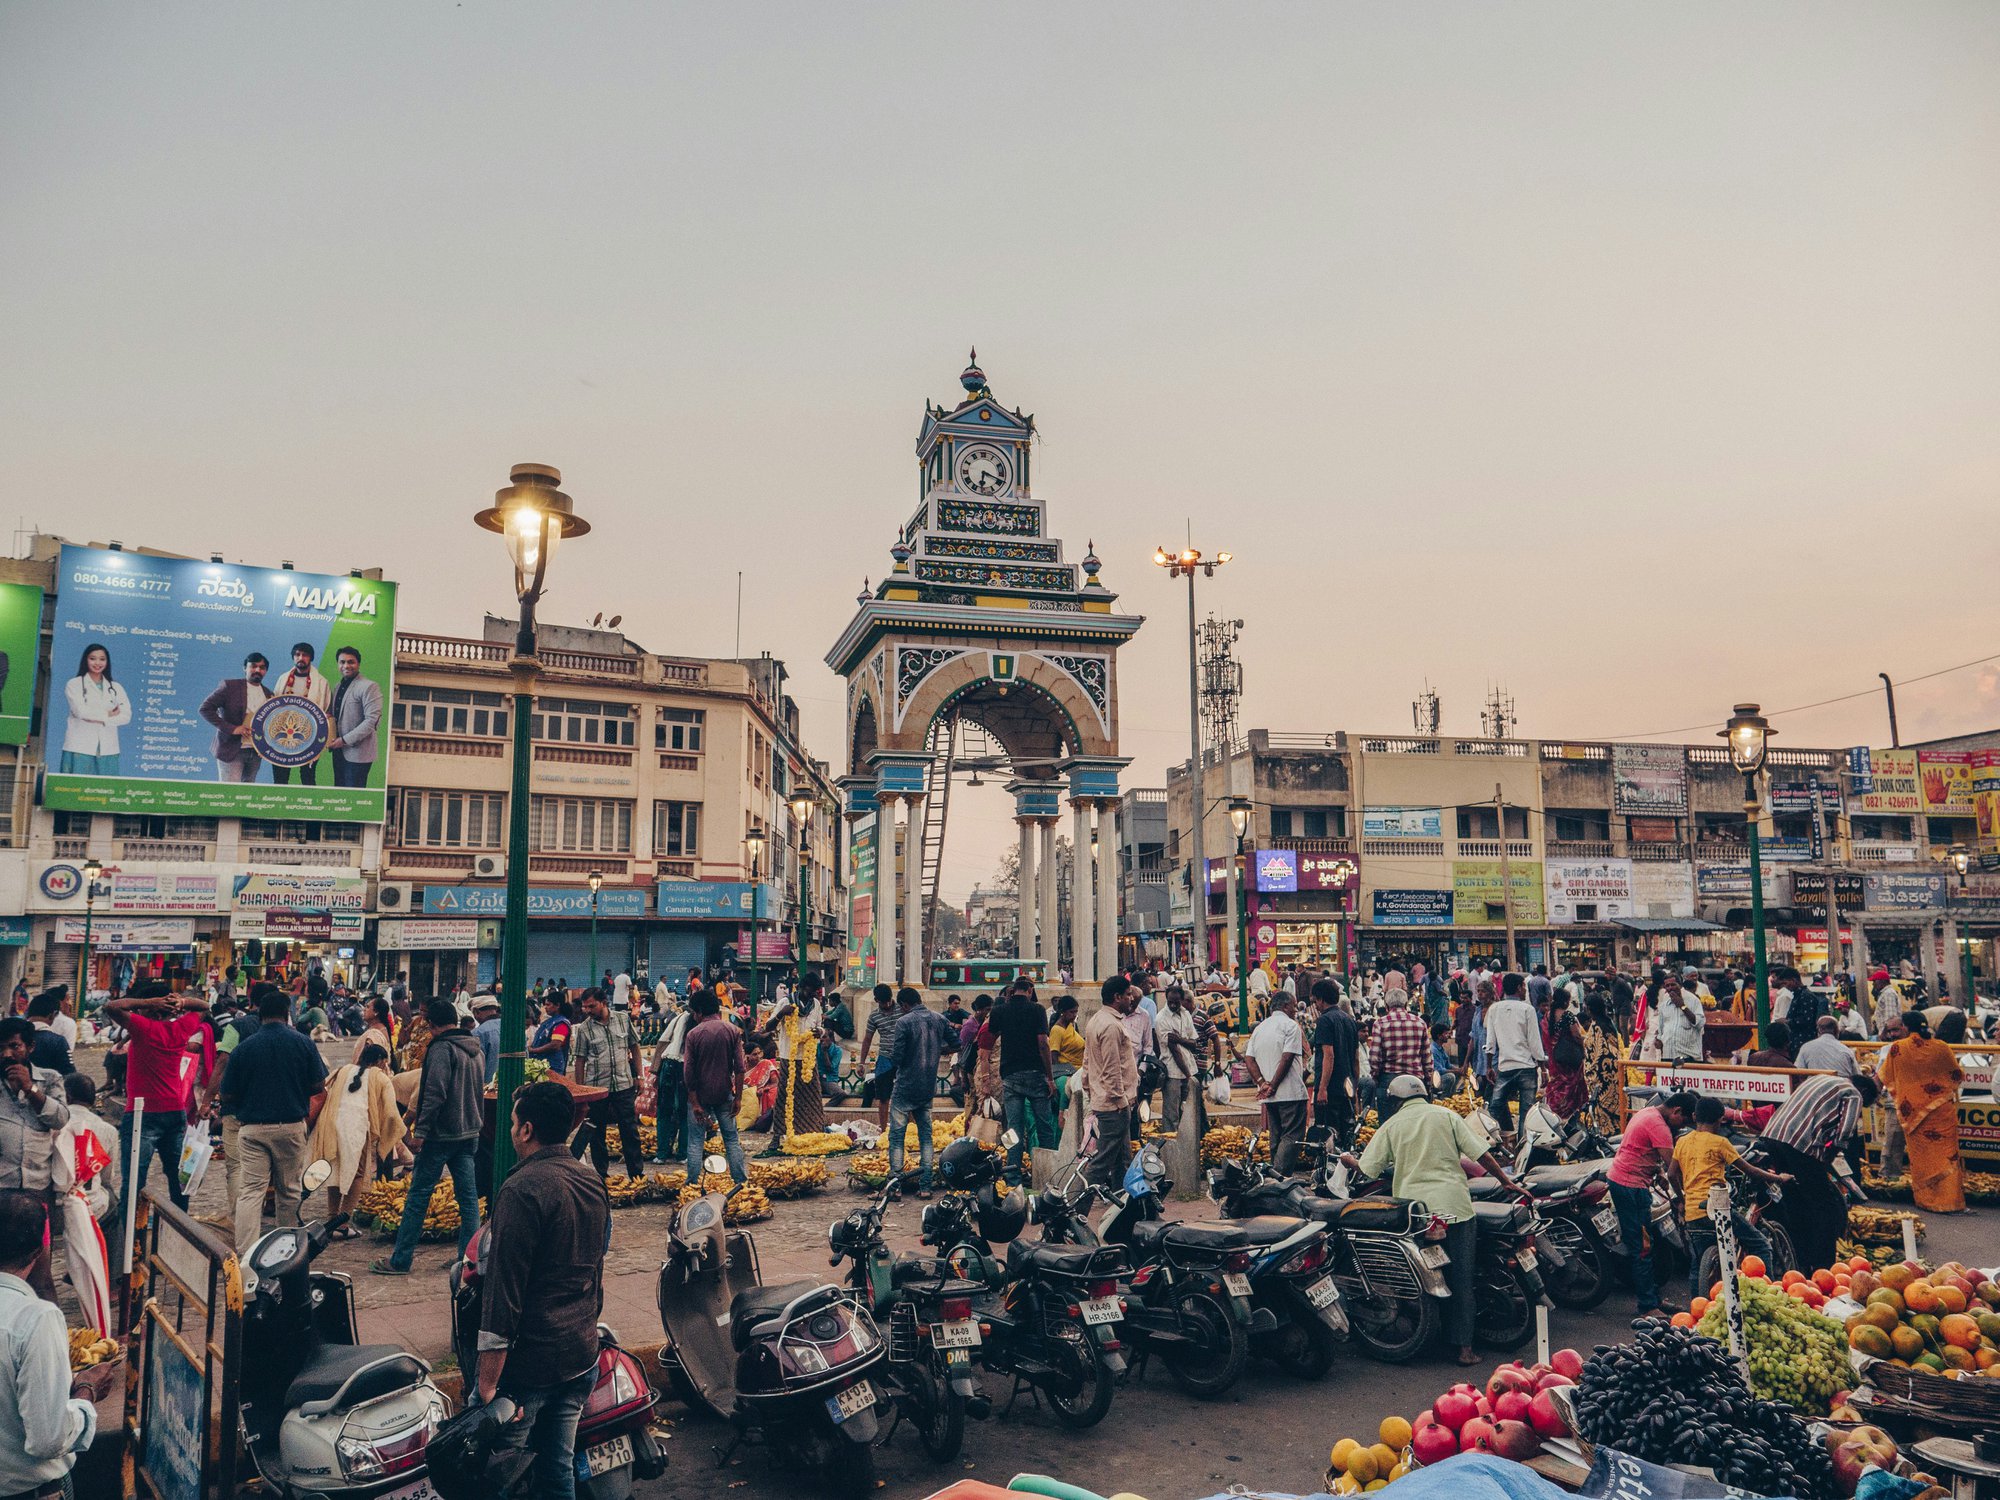
Modern grocery chains matter to packaged-food brands, but they represent only one route to consumers. Kiranas remain locally important, while large retailers increasingly connect stores, apps and fulfilment centres. A brand should choose accounts by target shopper, city, price point, pack size and fulfilment needs.
Consumer and format segmentation
Value supermarkets compete on staples, private labels and disciplined pricing. Hypermarkets add broader food and general merchandise ranges. Premium food stores serve imported, gourmet and fresh categories. Regional chains can offer denser local coverage than a national group. Compare the relevant format and banner, not only the parent company.
Online grocery and quick commerce
Retail apps and marketplaces support scheduled and rapid delivery, but their assortment, fulfilment and buying structures vary. Reliance describes JioMart as part of its digital commerce ecosystem. Other online and quick-commerce operators should be assessed as platforms with their own city coverage, dark-store networks, commissions and service standards rather than counted as supermarket branches.
Quick commerce is a separate format
Quick-commerce apps optimise a narrow local assortment for short delivery windows. They can be useful for impulse, convenience and replenishment missions, but they require different pack, inventory, promotion and availability decisions from a supermarket rollout. Platform presence does not prove nationwide physical retail distribution.
Retailer types that should not be ranked together
Consumer supermarkets, B2B wholesalers, government canteens, branded manufacturer outlets and convenience stores have different buyers and customers. Combining them by outlet count produces a misleading league table.
How this comparison works
We include formats with current primary evidence of grocery operations and describe their disclosed scope. Counts can cover different financial dates and definitions, so they are context rather than a ranking. Always confirm current buying contacts and supplier intake directly.
Compare active grocery retail groups in India
| Group or banner | Format and position | Current disclosed scope | Supplier relevance |
|---|---|---|---|
| Reliance Smart and Smart Bazaar | Supermarket and value hypermarket formats within Reliance Retail | Smart Bazaar passed 1,000 stores; Reliance reported 20,160 stores across all retail formats in FY2026 | Broad grocery scale; confirm the banner, category team and route into stores or JioMart |
| DMart | Value supermarket and hypermarket chain operated by Avenue Supermarts | 415 stores at 31 March 2025 | High-volume value retail; demonstrate price, rotation, replenishment and regional supply economics |
| Ratnadeep | Regional supermarket chain | Company reports more than 170 stores across Telangana, Karnataka and Andhra Pradesh | Useful for focused southern-city coverage and local execution |
| Star Bazaar | Supermarket and hypermarket concept operated principally through Trent Hypermarket | Trent reports 63 stores in 10 cities; Trent Hypermarket is a 50:50 Trent–Tesco venture | Food, fresh and FMCG route in selected cities; confirm format and city availability |
| Nature’s Basket | Premium and specialty food retail format in the Spencer’s Retail portfolio | 32 stores across Mumbai, Pune, Bengaluru, Kolkata and the Delhi NCR at FY2025 | Relevant to premium, gourmet and imported categories; confirm listing and import route |
Reliance Smart and Smart Bazaar
Reliance calls itself India’s largest grocery retailer and operates Smart, Smart Bazaar and JioMart within a wider retail portfolio. The group’s 20,160-store figure covers all formats, including non-grocery businesses; it is not the number of Smart or Smart Bazaar outlets. Reliance’s FY2026 chairman statement separately says Smart Bazaar crossed 1,000 stores.
DMart
Avenue Supermarts positions DMart as a value retailer for food, non-food FMCG and general merchandise. Its FY2025 annual report records 415 stores at year-end. A supplier proposition should fit DMart’s value positioning and demonstrate reliable regional replenishment rather than rely on a national-store assumption.
Ratnadeep
Ratnadeep describes a network of more than 170 stores across three southern states. Its concentrated footprint can make it a more relevant account than a larger national group for brands targeting Hyderabad, Bengaluru and adjacent markets.
Star Bazaar
Trent describes Star as a food-and-grocery concept covering staples, fresh food and FMCG. The business is primarily operated by Trent Hypermarket, its joint venture with Tesco. Its published footprint is 63 stores in 10 cities, so suppliers should confirm which formats and cities carry their category.
Nature’s Basket
Nature’s Basket is the clearer current specialty-food format in Spencer’s FY2025 disclosures, with 32 stores in five metropolitan markets. It can suit premium and imported products, although its scale and shopper proposition differ from a mass supermarket chain.
Regional and specialty retail
Heritage Fresh has a live consumer site and store finder in 2026, while Nilgiris reports more than 70 stores across more than seven cities. Both are current regional formats. Their legal buyer, franchise structure, operating locations and category contacts still need direct verification before a supplier approach. Other regional and international banners should be screened in the same way because public pages do not always distinguish operating stores from franchise rights.
B2B cash-and-carry is not a supermarket
METRO Wholesale India serves registered business customers, including traders, hotels, restaurants and caterers. Reliance Retail owns the business. METRO may be a valuable wholesale route, but it is not directly comparable with consumer supermarket banners. See our India food distribution guide for the role distinction.
Former and absorbed banners
Big Bazaar, Easyday and HyperCity should be treated as former or absorbed banners rather than current standalone buying networks. Reliance Smart Bazaar is the active Reliance format discussed above; the former Big Bazaar estate should not be counted again. Confirm the present banner and legal buyer instead of using historic outlet figures.
Other retail models
The Canteen Stores Department serves eligible defence personnel through a government system. Patanjali outlets primarily distribute a manufacturer-owned portfolio. 24Seven is a convenience-store model. These may be relevant for specific products, but their roles should be evaluated separately from general supermarket chains.
Compare grocery retail in other markets
For format context beyond India, compare the largest grocery chains in the United States and the largest supermarkets in Australia. Ownership concentration and buying structures differ, so do not transfer assumptions between markets.
A supplier entry checklist
- Choose the banner, cities and shopper mission before approaching the parent group.
- Confirm whether buying is national, regional, category-led or managed through a distributor.
- Verify FSSAI licensing and importer responsibility; see our India food import guide.
- Model listing, promotion, margin, returns, expiry, delivery and service-level costs.
- Ask for current supplier-onboarding instructions. Inclusion here does not mean a retailer is accepting new products.
Frequently asked questions
How large is India’s grocery market?
Published market estimates use different definitions and should not be mixed with store counts. For market entry, channel share in the target states and category is more useful than one national headline value.
Which grocery chain is largest?
Reliance describes itself as India’s largest grocery retailer. Its total store count covers the entire retail group, so use the separately disclosed Smart Bazaar scope when assessing that grocery format.
Which chain is growing fastest?
There is no comparable current dataset that proves one chain is the fastest-growing across the same period and store definition. Compare audited annual-report openings and closures for each operator instead.
What was India’s first online grocery store?
Several services preceded today’s large platforms, and “first” depends on whether the definition is a website, marketplace or full grocery operation. The distinction does not help supplier selection; current category reach and fulfilment performance do.
Plan an India retail entry
GourmetPro’s market-entry service helps food and beverage companies define priority channels, test retailer fit and build a practical route to market. Contact our team to discuss your product and target consumers.